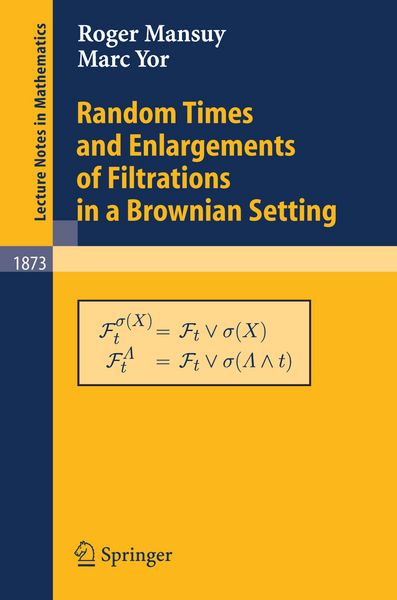
Random Times and Enlargements of Filtrations in a Brownian Setting
-
- Englisch ausgewählt
35,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Taschenbuch
Erscheinungsdatum
19.12.2005
Abbildungen
XIII, 158 p.
Verlag
Springer BerlinSeitenzahl
158
Maße (L/B/H)
23,5/15,5/1,1 cm
Gewicht
283 g
Auflage
2006
Sprache
Englisch
ISBN
978-3-540-29407-8
In November 2004, M. Yor and R. Mansuy jointly gave six lectures at Columbia University, New York. These notes follow the contents of that course, covering expansion of filtration formulae; BDG inequalities up to any random time; martingales that vanish on the zero set of Brownian motion; the Azéma-Emery martingales and chaos representation; the filtration of truncated Brownian motion; attempts to characterize the Brownian filtration.
The book accordingly sets out to acquaint its readers with the theory and main examples of enlargements of filtrations, of either the initial or the progressive kind. It is accessible to researchers and graduate students working in stochastic calculus and excursion theory, and more broadly to mathematicians acquainted with the basics of Brownian motion.
Ein neues Kapitel für Ihre Bücher
Ein neues Kapitel für Ihre Bücher
Schenken Sie Ihren alten Schätzen ein zweites Leben und erhalten Sie dafür eine Thalia Geschenkkarte.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice