KI-Beratung Beta

  • Produktbild: Econometrics in Theory and Practice
  • Produktbild: Econometrics in Theory and Practice

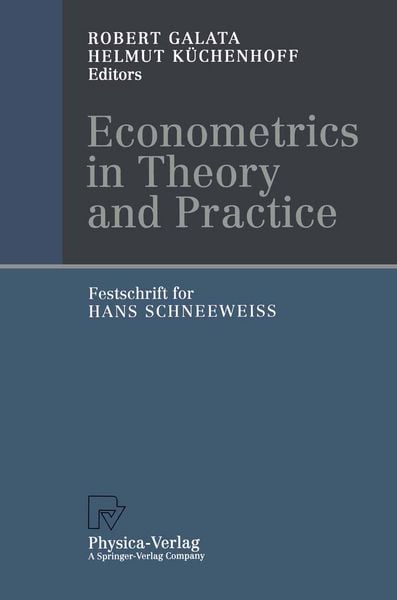
Econometrics in Theory and Practice Festschrift for Hans Schneeweiß

49,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

01.03.2012

Herausgeber

Robert Galata + weitere

Verlag

Physica

Seitenzahl

336

Maße (L/B/H)

23,5/15,5/1,9 cm

Gewicht

528 g

Auflage

Softcover reprint of the original 1st ed. 1998

Sprache

Englisch

ISBN

978-3-642-47029-5

Beschreibung

Portrait

Prof. Dr. Robert Galata, HS München, Fakultät Betriebswirtschaft hält seit mehreren Jahren Vorlesungen zum Thema Statistik

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

01.03.2012

Herausgeber

Verlag

Physica

Seitenzahl

336

Maße (L/B/H)

23,5/15,5/1,9 cm

Gewicht

528 g

Auflage

Softcover reprint of the original 1st ed. 1998

Sprache

Englisch

ISBN

978-3-642-47029-5

Herstelleradresse

Physica Verlag
Tiergartenstr. 17
69121 Heidelberg
DE

Email: ProductSafety@springernature.com

Ein neues Kapitel für Ihre Bücher

Ein neues Kapitel für Ihre Bücher

Schenken Sie Ihren alten Schätzen ein zweites Leben und erhalten Sie dafür eine Thalia Geschenkkarte.

Jetzt verkaufen
Jetzt verkaufen

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

  • Produktbild: Econometrics in Theory and Practice
  • Produktbild: Econometrics in Theory and Practice
  • Errors in Variables: C.-L. Cheng, J.W. Van Nees: Errors in Variables in Econometrics; W.A. Fuller: Estimation for the Nonlinear Errors-in-Variables Model; R.J. Carroll, J.D. Maca, S.J. Wang: Nonparametric Regression Splines for Generalized Linear Measurement Error Models; M. Thamerus: Different Nonlinear Regression Models with Incorrectly Observed Covariates; G. Schuster: ML Estimation from Binomial Data with Misclassifications; D.J. Bartholomew: The Indeterminancy of Latent Variable Models.- Theoretical Econometrics: M.J. Beckmann: An Introduction to the Economic Study of Knowledge; G. Ronning: Potentials and Limitations of Econometric Forecast and Simulation Models; H. Lütkepohl, D.S. Poskitt: Consistent Estimation of the Number of Cointegration relations in a Vector Autoregressive Model; Y. Feng, S. Heiler: Locally Weighted Autoregression; G. Tutz, G. kauermann: Locally Weigthed Least Squares in Categorical Varying-Coefficient Models; H. Toutenburg, G. Trenkler: Using First Differences as a device against Multicollinearity; W. Krämer: Asymptotic Equivalence of Ordinary Least Squares with Trending Regressors and Stationary Autoregressive Disturbances; G. Arminger: The Analysis of Growth and Learning Curves with Mean and Covariance Structure Models.- Applied Econometrics: K. Carstensen, G. Hansen: How Important are Real Shocks for the Real Exchange Rate?; G. Bamberg, G. Dorfleitner, K. Röder: Trading Strategies of a Financially Strong Investor in Futures and Stocks; H. Boscher, E.-M. Fromk, I. Pigeot: Estimation of the Stochastic Volatility by Markov Chain Monte Carlo; I. Brüggemann, J. Wolters: Money and Prices in germany; H.-J. Mittag, D. Stemann, B. Schipp: Quasi-Minimax Estimation, PriorInformation and Money Demand in Germany; W. Nagl: Bayesian Forecasting and Turning Points in Economic Cycles; L. Fahrmeir, C. Gieger, A. Klinger: Regression Approaches to Rental Guides; C. Pu, J. Frohn: An Econometric Model for the Transition Process of China's Economy.- Decision Theory and Statistics: F. Ferschl: Information Value as a Metacriterion for Decision Rules Under Strict Uncertainty; K. Weichselberger, T. Augustin: Analysing Ellsberg's Paradox by Means of Interval-Probability; H. Büning: Some Robust and Adaptive Tests Versus F-test for Several Samples; P.T. Wilrich: A Sequential Test for the Comparison of the Precision of Two Measurement Methods.- List of Publications of Hans Schneeweiß.