
Advanced Modelling in Mathematical Finance In Honour of Ernst Eberlein
-
- Hardcover
- Taschenbuch ausgewählt
- eBook
-
Sprache:Englisch
175,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Taschenbuch
Erscheinungsdatum
29.04.2018
Abbildungen
XXIV, 496 p. 79 illus., 69 illus. in color.
Herausgeber
Jan Kallsen + weitereVerlag
SpringerSeitenzahl
496
Maße (L/B/H)
23,5/15,5/2,8 cm
Gewicht
779 g
Auflage
Softcover reprint of the original 1st ed. 2016
Sprache
Englisch
ISBN
978-3-319-83390-3
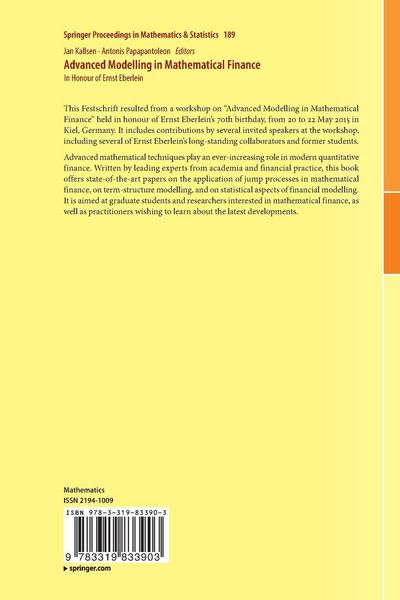
This Festschrift resulted from a workshop on “Advanced Modelling in Mathematical Finance” held in honour of Ernst Eberlein’s 70th birthday, from 20 to 22 May 2015 in Kiel, Germany. It includes contributions by several invited speakers at the workshop, including several of Ernst Eberlein’s long-standing collaborators and former students.
Advanced mathematical techniques play an ever-increasing role in modern quantitative finance. Written by leading experts from academia and financial practice, this book offers state-of-the-art papers on the application of jump processes in mathematical finance, on term-structure modelling, and on statistical aspects of financial modelling. It is aimed at graduate students and researchers interested in mathematical finance, as well as practitioners wishing to learn about the latest developments.
Ein neues Kapitel für Ihre Bücher
Ein neues Kapitel für Ihre Bücher
Schenken Sie Ihren alten Schätzen ein zweites Leben und erhalten Sie dafür eine Thalia Geschenkkarte.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice