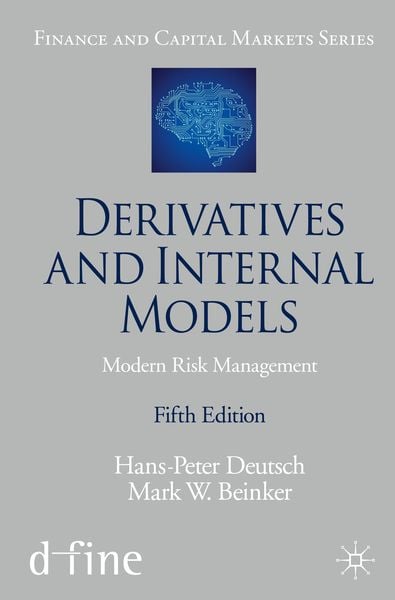

Derivatives and Internal Models Modern Risk Management
-
- Hardcover
- Taschenbuch ausgewählt
- eBook
-
Sprache:Englisch
63,99 €
inkl. gesetzl. MwSt.,
Beschreibung
Produktdetails
Einband
Taschenbuch
Erscheinungsdatum
23.10.2020
Verlag
SpringerSeitenzahl
897
Maße (L/B/H)
23,5/15,5/5 cm
Gewicht
1381 g
Auflage
Fifth Edition 2019
Sprache
Englisch
ISBN
978-3-030-22901-6
Now in its fifth edition, Derivatives and Internal Models provides a comprehensive and thorough introduction to derivative pricing, risk management and portfolio optimization, covering all relevant topics with enough hands-on, depth of detail to enable readers to develop their own pricing and risk tools.
The book provides insight into modern market risk quantification methods such as variance-covariance, historical simulation, Monte Carlo, hedge ratios, etc., including time series analysis and statistical concepts such as GARCH Models or Chi-Square-distributions. It shows how optimal trading decisions can be deduced once risk has been quantified by introducing risk-adjusted performance measures and a complete presentation of modern quantitative portfolio optimization. Furthermore, all the important modern derivatives and their pricing methods are presented; from basic discounted cash flow methods to Black-Scholes, binomial trees, differential equations, finite difference schemes, Monte Carlo methods, Martingales and Numeraires, terms structure models, etc.
The fifth edition of this classic finance book has been comprehensively reviewed. New chapters/content cover multicurve bootstrapping, the valuation and hedging of credit default risk that is inherently incorporated in every derivative—both of which are direct and permanent consequences of the financial crises with a large impact on our understanding of modern derivative valuation.
The book will be accompanied by downloadable Excel spread sheets, which demonstrate how the theoretical concepts explained in the book can be turned into valuable algorithms and applications and will serve as an excellent starting point for the reader’s own bespoke solutions for valuation and risk management systems.
Ein neues Kapitel für Ihre Bücher
Ein neues Kapitel für Ihre Bücher
Schenken Sie Ihren alten Schätzen ein zweites Leben und erhalten Sie dafür eine Thalia Geschenkkarte.
Noch keine Bewertungen vorhanden
Verfassen Sie die erste Bewertung zu diesem Artikel
Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.
Kurze Frage zu unserer Seite
Vielen Dank für Ihr Feedback
Wir nutzen Ihr Feedback, um unsere Produktseiten zu verbessern. Bitte haben Sie Verständnis, dass wir Ihnen keine Rückmeldung geben können. Falls Sie Kontakt mit uns aufnehmen möchten, können Sie sich aber gerne an unseren Kund*innenservice wenden.
zum Kundenservice